
Concept imagery
Your business was built to grow. Your wealth must be built to last.
BUSINESS · CAPITAL · LEGACY
Business success.
Personal independence.
Different decisions.
A company can fund a family’s life, carry its borrowing and hold most of its wealth at the same time. As the business grows, those connections deserve a deliberate review.
Promoter Wealth Architecture is NNRC’s approach to connecting business capital, family income, protection and succession. We organise the facts, clarify the decisions and coordinate agreed next steps with the relevant professionals and authorised providers.
Make the important
decisions connect.
A collection of products cannot, on its own, answer these questions. The work begins with the structure around your business, your capital and your family.
01A valuable business. Limited personal liquidity.A substantial valuation may leave little capital available for family needs.Agreed work productCapital & ownership map
Distinguish business interests from personally accessible assets, liabilities and commitments. Identify what is available, what is pledged and what needs verification.
02Surplus has several competing demands.Reinvestment, debt commitments and family needs can draw on the same pool.Agreed work productCapital-flow brief
Document how money moves between the business and family, the purpose of each movement and the decisions requiring commercial, tax or legal review.
03Tax, ownership and access pull in different directions.A tax benefit alone does not establish whether an arrangement serves the family.Agreed work productSpecialist decision brief
Set out the intended purpose, time horizon, costs and access needs. The relevant qualified professional evaluates lawful options and their implications.
04Business obligations can reach the family balance sheet.Guarantees, secured assets and key-person dependence deserve a connected view.Agreed work productExposure & protection register
Bring borrowing commitments, guarantees, family dependencies and existing cover together. Coordinate the appropriate legal, insurance and contingency-liquidity review.
05A successor does not replace the founder’s income.Stepping back changes your role. It does not automatically fund your lifestyle.Agreed work productFamily-income & transition brief
Clarify spending commitments, income sources, available personal capital and the proposed handover. Prepare the inputs for scenario work under the appropriate engagement.
06Ownership can pass before expectations are clear.Leadership, ownership and income are different decisions for a business family.Agreed work productSuccession & continuity brief
Record the decisions around active and non-active family members, distributions, responsibilities and access to records. Coordinate the relevant legal and governance work.
These are potential outputs of a separately agreed engagement. NNRC’s role is discovery, factual mapping and coordination. Personalised securities or asset-allocation recommendations require a separately identified, appropriately authorised engagement; tax and legal conclusions remain with the relevant qualified professional.
What would fund your life
if you stepped back?
The personal capital intended to support your chosen life with less reliance on ongoing business distributions.
Your requirement depends on your family’s commitments, other income, usable assets and the assumptions being tested. It is a planning range to review over time.
Different purposes. A considered connection.
Personalised calculations and investment recommendations require the appropriate professional engagement. Assumptions about inflation, tax, costs, longevity and risk matter; no capital amount guarantees an outcome.
From understanding to follow-through.
Assess. Reframe. Keep on course. A practical pathway with a defined output at each stage.
See the connections. Name the gaps.
Bring business interests, personal assets, cash flows, commitments and guarantees into one factual picture.
Agreed outputs: a capital map, an exposure register and the priority questions for professional review.Discuss my wealth picture
Give each part of your capital a job.
Distinguish enterprise needs, family income and longer-term ambitions. Prepare the inputs for Freedom Capital scenarios and the relevant specialist decisions.
Agreed outputs: a family-income brief, a succession brief and clearly scoped specialist workstreams. Personalised investment recommendations require the appropriate authorised engagement.Discuss my priorities
Make the blueprint actionable.
Coordinate agreed work with the responsible professionals and authorised providers. Record decisions, outstanding actions and the changes that should prompt a review.
Agreed outputs: an implementation tracker with named owners, dependencies and review dates. Ongoing coordination is included only where agreed.Discuss my next step
Begin with a conversation. The Promoter Wealth Diagnostic identifies the priority questions with CA Sanjay. Maps, specialist work and ongoing reviews are separately scoped; a first conversation is not a completed financial plan.
A founder’s experience.
A promoter’s perspective.
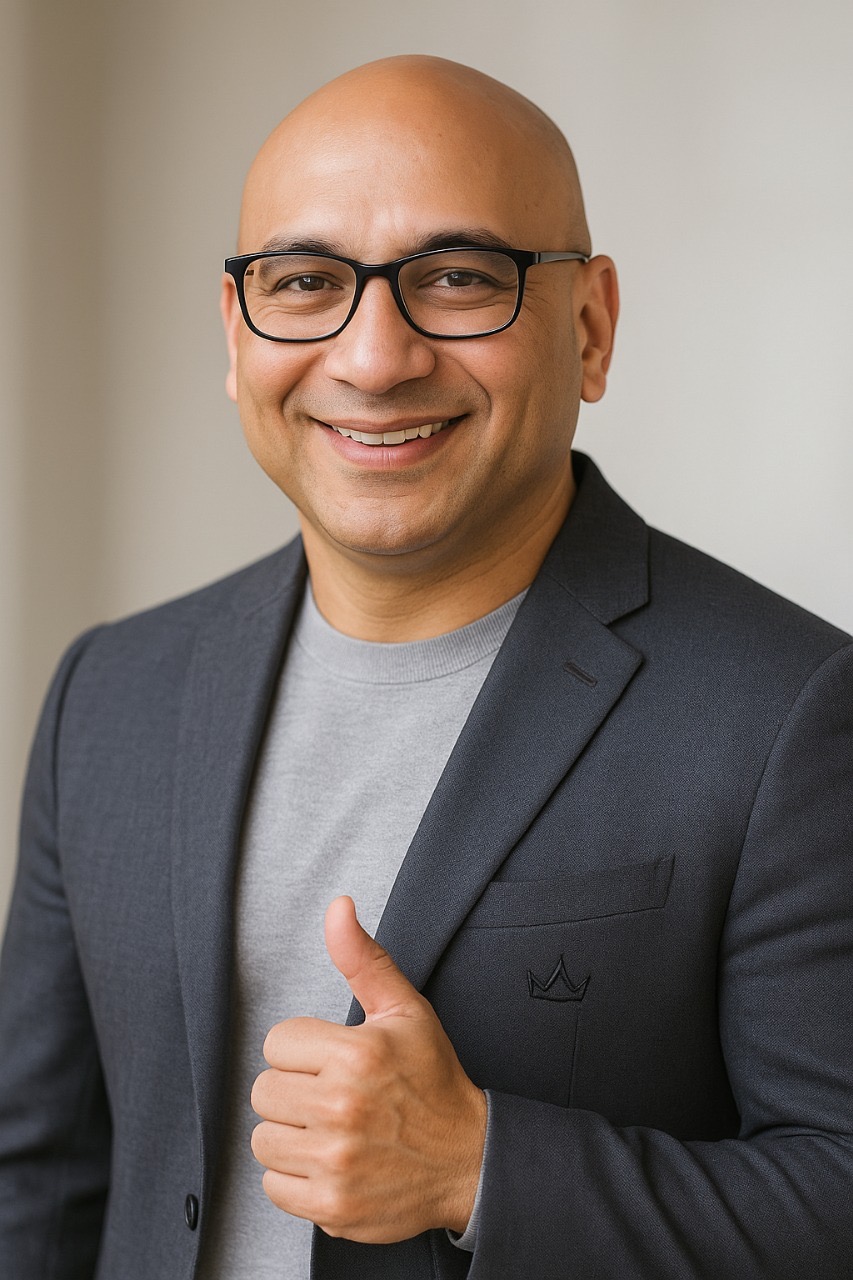
CA Sanjay Ray Chowdhury co-founded and exited RussAir. He has lived the decisions behind the balance sheet: cash flow, reinvestment, ownership and the transition beyond a business. That experience shapes the questions NNRC asks—and the connections it helps you make.
CA Sanjay Ray Chowdhury
Chartered Accountant · Founder, Niel N Ray Capital
Have a specific requirement? Start there.
A clearer beginning.
What is Promoter Wealth Architecture?
PWA is NNRC’s approach to connecting the decisions around business capital, personal income, family exposures and succession. It starts with a factual picture and a sequence of priorities. Specialist advice and regulated services are separately scoped with the responsible professional or authorised provider.
Do I have to sell the business to pursue financial independence?
No. The starting question is how your family’s needs are funded and what depends on your continued involvement. A business may remain central to the family. Any change to ownership, distributions or investment arrangements needs a considered assessment of your circumstances.
Is there one Freedom Capital number for every promoter?
No. Lifestyle, commitments, available assets, other income and time horizons differ. A properly scoped assessment considers scenarios and review points. A universal spending multiple cannot capture those differences.
What do I receive from the first conversation?
The guided Promoter Wealth Diagnostic with CA Sanjay identifies the questions that deserve attention and an appropriate next step. It is not an online calculator or a completed financial plan. Any further work, deliverables, responsibilities and fees are agreed before proceeding.
Build the business for growth.
Prepare your wealth for choice.
Begin with the decision that matters now: surplus, personal income, protection or the eventual handover.
Khar West, Mumbai · By prior appointment